Home Insurance and homeownership typically go hand-in-hand. In fact, if you have a mortgage on your home, your lender requires you to have it. But even if you don’t have a mortgage, most homeowners get a home insurance policy in place to protect them against financial loss due to fire, storms, theft, vandalism and legal liability.
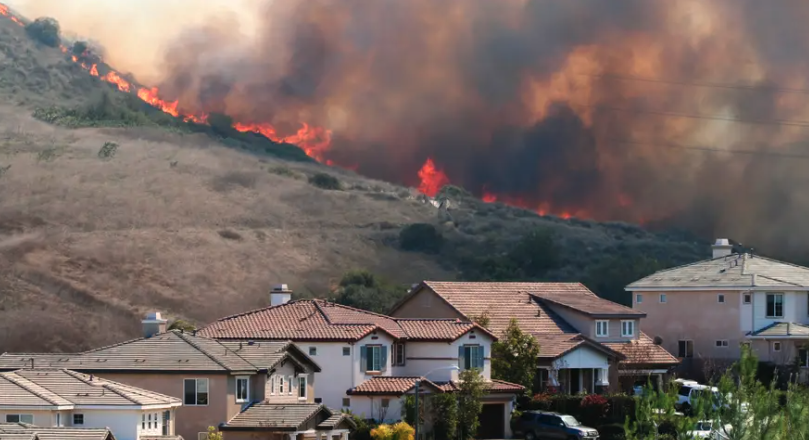
But recent events are causing consumers and the industry to rethink things. The perfect storm of increasing materials and labor costs, inflation and natural disasters due to climate change, have majorly impacted the industry. And the impact can be felt everywhere, including Wisconsin, even though we live in a state not in high risk of wildfires, tornadoes, hurricanes, earthquakes or floods.
With the increasing incidence of natural disasters creating damage and losses throughout the country, insurance companies (who also have insurance) are forced to pass increased costs on to policyholders in order for them to have enough money in their claims reserves to pay out the higher losses. And while consumers are protected from haphazard increases as insurance companies must file for rate increases with the Department of Insurance in each state it operates, they are still feeling the pain of affordability.
According to Bankrate, “since insurance is a shared risk pool, you are sharing in the claims and profitability of your insurance company, good or bad. When an insurance company has to pay out for natural disasters in one area, it can impact the insurance rate of all of its policyholders, especially those in states likely to experience more catastrophic losses in the future.”
And homeowners aren’t just seeing their rates increase due to extreme weather impact, some big insurers are even scaling back or withdrawing their coverage in specific areas altogether to avoid paying for damage, in turn requiring homeowners to find alternatives, usually at a higher cost and less protection.
We spoke with local insurance broker and owner of Elevated Insurance, Jackson Bubolz – and former client of Team Trimble – who agrees that we are in a “hard market” – when carriers are no longer competing to offer you the lowest price, so they can remain profitable. But he also thinks this should lift by 2025, reminding us that “soft markets have been 80% of the markets we’ve experienced the last 20 years.”
Until then, he advises homeowners to control what they can control, and work with a broker who can offer you several options.
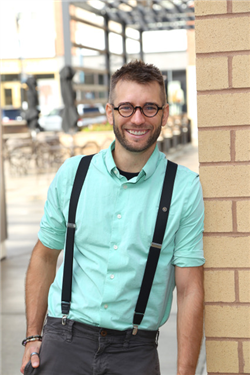
Jackson Bubolz
Local insurance expert, owner of Elevated Insurance
262.424.0420
Elevatedins.com
Get Home, Auto, or Life quote“If you like your agent, ride it out. Have them shop for you if the increase isn’t palpable. If you don’t love your agent, switch. There are complacent and hungry businesses. Don’t get stuck in a complacent one when you need something to happen,” Jackson.
Q&A with Jackson Bubolz, local insurance expert
Why is it important that homeowners find the right provider for their needs?
Your insurance agent could be the last advocate between you and bankruptcy. Finding someone who will take care of you when you need them only costs you your time, and the impact can be tremendous.
Why might a homeowner go with a broker like you over a big box?
Big boxes that you might associate with insurance, like Amfam and Statefarm, work for their carrier, where the bottom line is profitability. As an independent broker, my priority lies with working for my clients, educating them and offering the best from a range of carriers. If you were to meet with me, you’d get a tailored level of service for my consultation, and a complimentary quote – yes, all without charge! Payments only begin when you decide to partner with us.
How else are you different to your competitors?
We take the time to educate our clients on their options and tailor solutions to their needs and risk tolerances. Since we are independent agents, we are free to choose a carrier that best meets your needs. We also make donations (including one for each complimentary quote we provide), do volunteer work, host a book club and giving library, answer phone calls and return emails. We feel that is different than how the competition does their job.
What are the most important things to consider when buying homeowner’s insurance?
Coverage components, dwelling value, sewer and drain back up, understanding your choices for deductibles.
What are the biggest mistakes or “uh ohs” you see when working with clients?
A lot of people think choosing insurance is as simple as a cable package. They don’t understand the intricacies and nuances to all the different types of coverage and how it impacts them. If an insurance buyer doesn’t have someone talk through all these things, there could be assumptions made, and this usually causes disappointment.
What advice would you give to homeowners in the current market?
Shop every three years. Bundle. Work with a broker.